Xactimate is the estimating software most insurance adjusters use to price roof claims. When your roofer writes the estimate in Xactimate too, both estimates use the same line items and the same local pricing. That makes it easy to spot what the adjuster missed and submit a supplement for it. The result is that more of your roof gets paid for by the policy you already carry.
Roofer Xactimate insurance estimate is a phrase you will hear once your claim is open, and whether your roofer speaks that language decides how much of your roof the insurer actually pays for.
After a storm rolls through Horry, Georgetown, or Brunswick County, most homeowners want two things. You want the roof fixed, and you want the claim to cover what it should. Then the adjuster's estimate arrives. It's a long printout full of codes, quantities, and prices, and it rarely matches the number your roofer gave you.
That gap is where many homeowners lose money. The good news is that it's usually not a mystery. It mostly comes down to whether both sides are working from the same pricing book. This guide explains what Xactimate is, why it matters to your claim, and what to ask a roofer before you sign anything.
Table of Contents
- What Is Xactimate, and Why Does Your Insurer Use It?
- Do Insurance Companies Really Price Roof Claims in Xactimate?
- Why Should Your Roofer's Estimate Match the Adjuster's Format?
- What Can a Roofer Catch That an Adjuster Might Miss?
- Why Is the Roofer's Estimate Different From the Adjuster's?
- What Is a Supplement, and How Does It Get Approved?
- Can You Get an Xactimate Estimate on Your Own?
- What Should You Ask a Roofer Before You File or Sign?
- How Can Linta Roofing Help With Your Claim?
- Frequently Asked Questions
What Is Xactimate, and Why Does Your Insurer Use It?
Xactimate is estimating software made by Verisk. Insurance carriers and independent adjusters use it to price property damage, including roofs. It breaks a job into individual line items such as tear-off, underlayment, drip edge, flashing, and ridge vents. Each line carries a price based on labor and material costs for your local market.
Think of it like a restaurant menu. Every dish has a set price before you order. Xactimate does the same for every part of a roof replacement, so the adjuster isn't guessing at a total.
Insurers like it because it's consistent. Two adjusters pricing the same roof in the same area should land in a similar place. For the bigger picture of how an adjuster reaches a number, our guide on how insurance companies determine roof cost walks you through it.
Do Insurance Companies Really Price Roof Claims in Xactimate?
Xactimate, which is made by Verisk, is the estimating platform we see on the large majority of claims we work in Horry and Georgetown counties. A few carriers use other programs, and those follow the same line-item approach.
For you, this means the adjuster's estimate is almost always a list of line items, not a single price. Your roof insurance claim payout is built from those lines, minus your deductible and any depreciation held back. If a line is missing, it isn't paid.
Why Should Your Roofer's Estimate Match the Adjuster's Format?
A lump-sum bid gives the adjuster nothing to compare. A single figure for "full roof replacement" can't be checked against a 40-line estimate. In that situation, the adjuster will usually stick with their own numbers.
An Xactimate estimate from your roofer lines up with the adjuster's report item by item. If the adjuster priced 28 squares and your roof measures 32, it shows. If ice and water shield or starter strip is missing, that shows too.
Here's a simple example. Say the adjuster approves new shingles but leaves out drip edge, which current code requires on a replacement. On a lump-sum bid, that cost quietly lands on you. On an Xactimate estimate, your roofer adds the missing line at the same price the insurer already uses. The request is hard to dismiss because it's built on the insurer's own data.
That's why Linta Roofing writes its insurance claim estimates in Xactimate.
What Can a Roofer Catch That an Adjuster Might Miss?
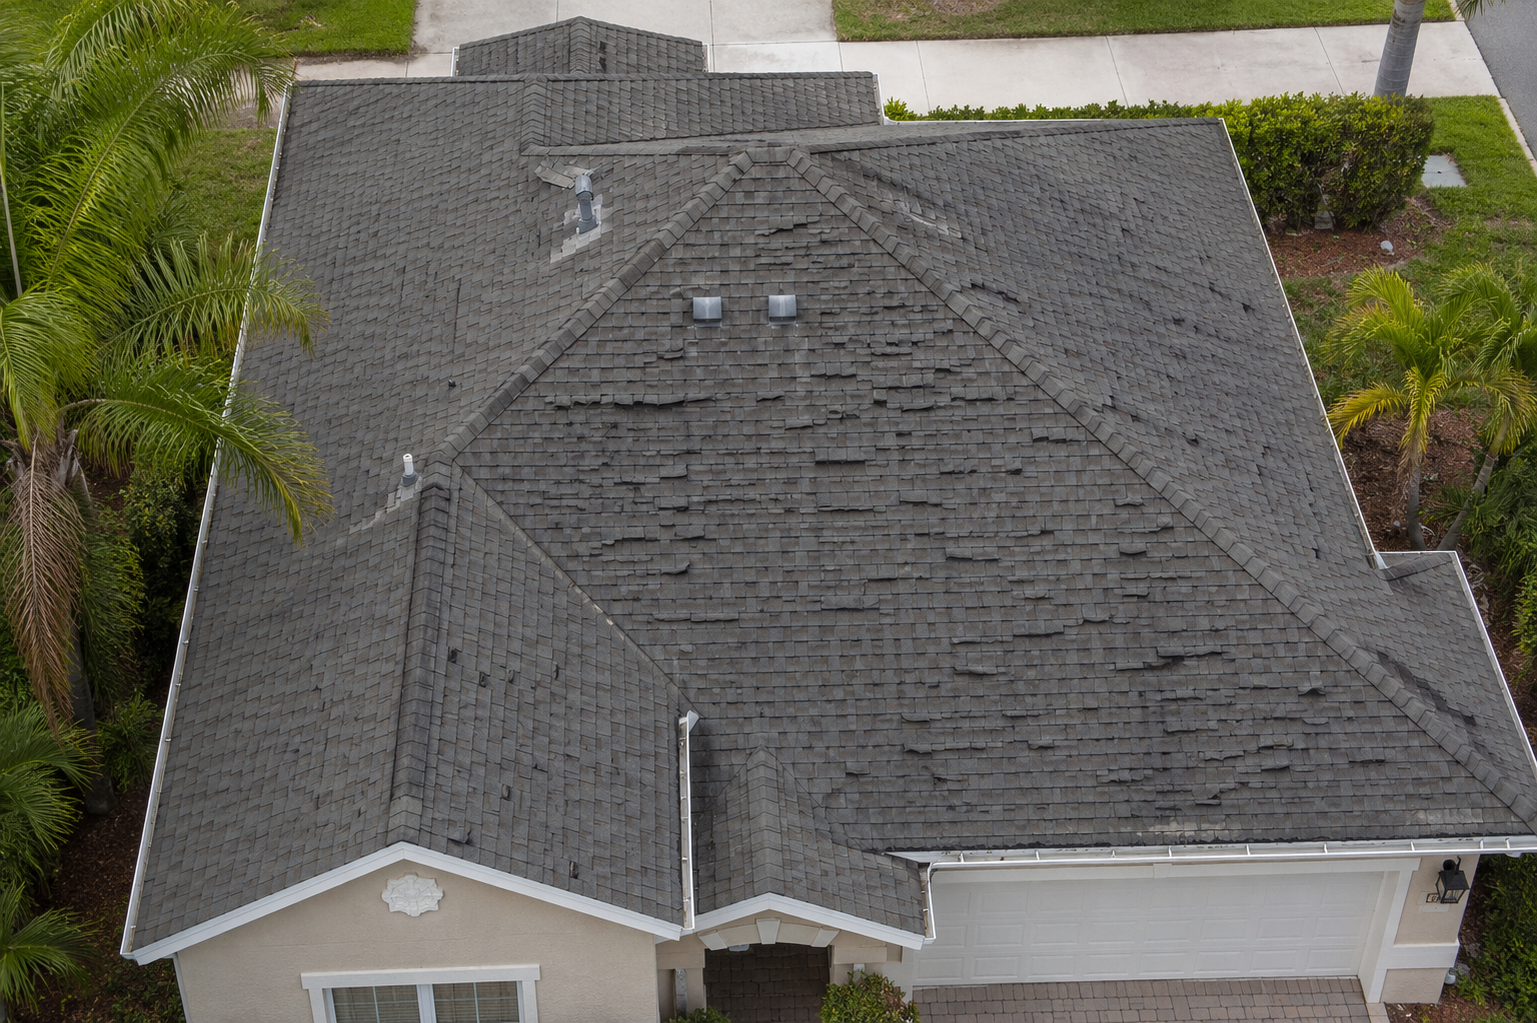
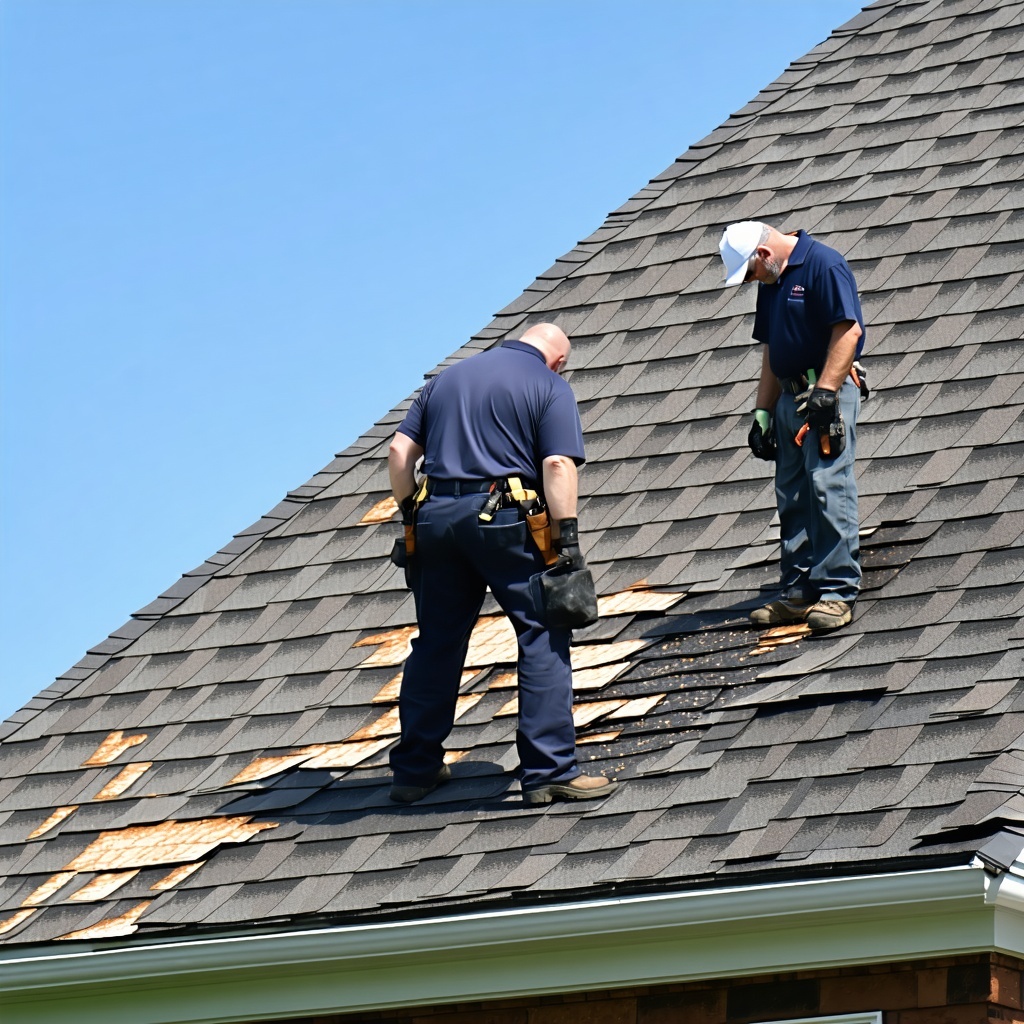
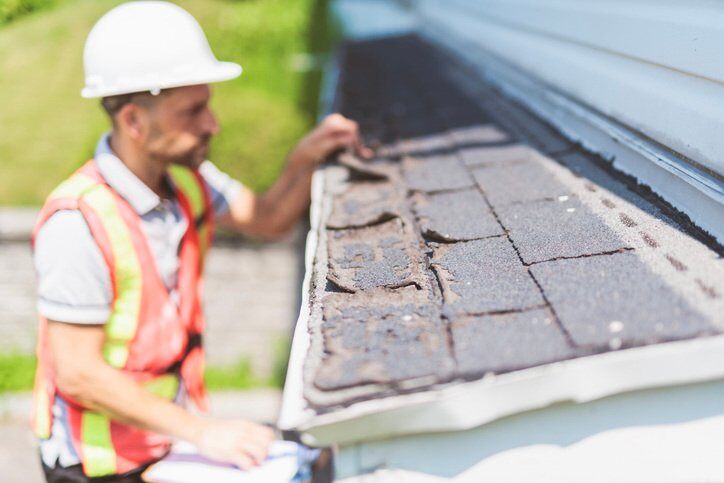
After a big storm, adjusters may inspect dozens of homes in a week. Small items get skipped. These are the ones we see most often:
- Measurement gaps. Square counts, waste factor, and steep-pitch charges.
- Code upgrades. Items current building code requires that the old roof didn't have.
- Accessories. Drip edge, starter strip, ridge cap, pipe boots, flashing, and vents.
- Labor items. Removing extra shingle layers, high-roof charges, and permits.
- Related damage. Gutters, skylights, and soft metals dented by hail.
Linta Roofing inspects storm damage to the same engineering standard insurers use to decide whether a claim is covered. Their project managers are HAAG trained, the damage assessment is free, and they meet your adjuster at the house so the approval reflects current building code instead of leaving you to pay the difference.
Why Is the Roofer's Estimate Different From the Adjuster's?
A different number doesn't mean anyone is being dishonest. It usually comes from one of a few honest gaps. The adjuster may have measured differently, missed an accessory, or judged a slope as undamaged when the roofer found hail bruising.
Depreciation also plays a part. Many policies pay the actual cash value first and hold back the rest until the work is finished. If the two figures confuse you, our explainer on ACV vs RCV roof insurance breaks down the difference.
When both estimates are in Xactimate, you can see exactly which lines differ. That turns a confusing argument about totals into a short list of specific items to resolve.
What Is a Supplement, and How Does It Get Approved?
A supplement is a request to add items or costs that weren't in the original approved estimate. It's a normal part of the claim process.
Supplements happen for two main reasons. Something was missed in the first estimate, or something new is found during the job. Rotted decking under the old shingles is a common example in our humid coastal climate.
A supplement that gets approved usually follows these steps:
- Your roofer documents the item with photos, measurements, and any code requirement.
- The roofer adds it as an Xactimate line item that matches the insurer's pricing.
- The adjuster reviews it and approves, adjusts, or denies the line.
Once the work is complete, you may also be owed money the insurer held back at the start. Our guide to recoverable depreciation on a roof claim explains how to collect it.
Linta Roofing has helped thousands of homeowners manage the roof insurance claim process over the last 40 years and more. That volume is why they have a clear 3-step process and do not improvise per storm.
Can You Get an Xactimate Estimate on Your Own?
In theory, yes. In practice, it isn't easy. Xactimate is a paid professional subscription built for contractors and adjusters, and it takes training to use well.
There are two simpler routes. First, ask your insurer for a copy of the adjuster's estimate so you can see every line item. Second, work with a roofer who writes estimates in Xactimate and will walk you through the comparison. Linta Roofing's storm damage insurance assistance covers both the inspection and that side-by-side review.
What Should You Ask a Roofer Before You File or Sign?
A few direct questions will tell you a lot about how a roofer handles insurance work:
- Do you write insurance estimates in Xactimate?
- Will you meet my adjuster at the house?
- How do you document and submit supplements?
- What would this roof cost if I paid without insurance?
That last question matters more than people expect. Linta Roofing publishes what a roof costs on its website, so you can see the price before you ever speak to a salesperson. The published price is the price everyone pays.
How Can Linta Roofing Help With Your Claim?
 Linta Roofing is a family-owned, GAF Master Elite certified roofer founded in 1948 and serving the Grand Strand since 1985.
. Every project gets a dedicated superintendent, workmanship warranties run up to 25 years, and a real-time app lets you track your job from start to finish.
You don't have to decode an adjuster's estimate alone. If a storm has hit your roof, contact our team to schedule a free inspection. We'll show you exactly what's covered and what may still be missing.
Frequently Asked Questions
What is Xactimate?
Xactimate is estimating software from Verisk that insurers, adjusters, and contractors use to price property damage. It lists each part of a repair as a line item with a local price.
Do insurance companies use Xactimate for roof claims?
Most U.S. property insurers and independent adjusters use Xactimate to price roof claims. A few use similar line-item programs.
Can a homeowner get an Xactimate estimate?
You can ask your insurer for a copy of the adjuster's Xactimate estimate. For your own estimate in the same format, work with a roofer who uses Xactimate for claims.
Why is the roofer's estimate different from the adjuster's?
The gap usually comes from different measurements, missed accessories, code upgrades, or depreciation. Matching Xactimate estimates show exactly which line items differ.
What is a supplement on a roof insurance claim?
A supplement is a request to add costs that weren't in the original estimate. It's used for missed items or damage found during the job, such as rotted decking.
Topics: